Benefits OnLine

Screenshots
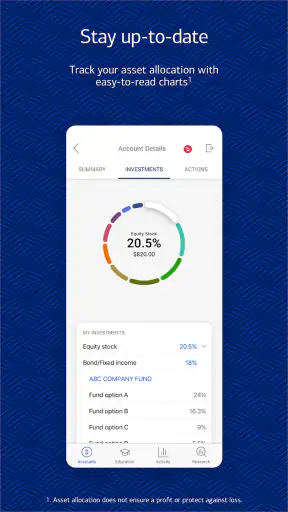
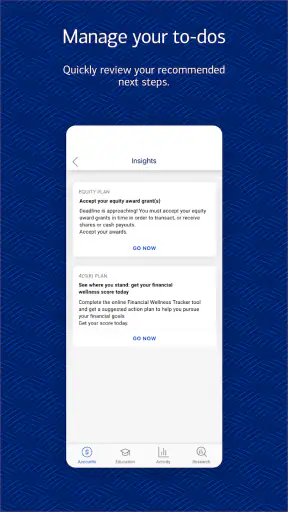
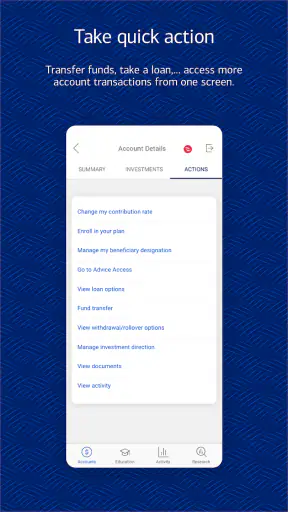
Details
- Rating
- 1.06K reviews
- Version
- 26.08.02
- Developer
- Merrill Lynch, Pierce, Fenner, and Smith Inc.
Analysis by Norviv
When retirement or workplace benefits are spread across employer paperwork, provider portals, and occasional decisions you would rather not postpone, a focused account-management app can be useful. I reviewed Benefits OnLine as a finance app from Merrill Lynch, Pierce, Fenner, and Smith Inc., and its purpose is clear: it is built around retirement and benefit services rather than general banking or everyday spending.
That narrow focus is both its main strength and its first limitation. I would recommend it to someone whose employer or plan is connected with Merrill Lynch and who wants a more convenient way to check benefit information on a phone. I would not choose it as a replacement for a full personal-finance app, a budgeting tool, or a universal retirement tracker. It works best when it is treated as a practical doorway into an existing benefits relationship, not as a complete financial command center.
Following a benefits task from question to outcome
When I follow a benefits task from the first question to its outcome, I try to define what would count as a useful answer before opening the account: a confirmed detail, a next step, or a question for the plan administrator. That small preparation makes it easier to judge whether the session actually resolved anything. It also sets up the next section’s focus on turning a quick check into a clear, deliberate account journey.
Starting with the right question
The most useful way to approach this app is to begin with a specific need. Perhaps I want to check my retirement account after changing jobs, review information connected to an employer benefit, or confirm that I am looking in the correct place before contacting a plan administrator. Benefits OnLine is more suitable for those focused questions than for casually browsing financial information.
That distinction matters because retirement decisions are often slowed by uncertainty rather than by a lack of information. I may not need a dozen financial tools open at once; I may simply need to reach the relevant benefits area, understand what is displayed, and decide whether the next step belongs to me, my employer, or the plan provider. A dedicated app can reduce that initial searching, provided my benefits relationship is supported.
The app is free to install and carries an Everyone content rating, which makes it approachable for a broad audience. Its current version is 26.08.02, and it requires at least iOS or Android 11. That operating-system requirement is worth checking before downloading, especially if I keep an older phone for financial tasks. A free app is not especially helpful if the device cannot run it or if the phone is shared with someone using an older system.
Moving through the account journey
My first practical step would be installing the app, opening it, and identifying the correct sign-in route for my benefits relationship. I would keep employer or plan information nearby rather than trying to guess which account applies. Retirement services can involve several similar names, and entering the wrong path can create unnecessary confusion before I even reach the information I need.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
After signing in, I would resist the temptation to treat the first screen as the whole story. The useful result is not simply seeing an account label; it is connecting that information to a decision. If I am checking a retirement benefit after leaving an employer, I would note what is shown, identify which action is available to me, and write down any question that still requires assistance. This turns the app from a passive viewer into one part of a deliberate workflow.
A good habit is to use the app when I have enough time to read carefully. Retirement and benefit screens can contain terms that are easy to skim past, particularly when I am checking them between errands. I would avoid making a rushed choice from a phone screen just because the app makes access convenient. Convenience should shorten the path to understanding, not replace understanding.
The most valuable workflow is question, verification, then action. I would first define what I need to know, verify that the displayed benefit or account is the one I intended to review, and only then decide whether to continue inside the app or contact the responsible support channel. This simple order helps prevent a common mistake: confusing access to information with confirmation that a change has been completed.
Using the app as a checkpoint, not a financial plan
Benefits OnLine makes more sense when it sits inside a wider routine. I might use a budgeting app to understand monthly cash flow, a spreadsheet to compare long-term goals, and this app to review the retirement or workplace-benefit information connected to Merrill Lynch. Those tools answer different questions. A general finance app may provide a broader view of household money, while Benefits OnLine is more relevant to the specific benefits relationship it serves.
This separation can actually improve clarity. Instead of expecting one app to explain spending, savings, investments, insurance, and employment benefits together, I can use each tool for the information it is designed to present. The trade-off is that I may need to move details between systems manually when building a complete personal picture. For someone who values one dashboard above all else, that extra handoff may feel inconvenient.
Where the handoffs happen
The most important handoff is between the app and the employer or plan administrator. If I see information that looks incomplete, outdated, or inconsistent with a recent employment change, the app may be the place where I notice the issue, but not necessarily the place where it can be resolved. I would record the relevant details, check any available instructions, and contact the responsible party rather than repeatedly refreshing the same screen.
Another handoff occurs between digital information and personal records. For a retirement review, I would keep a dated note of what I checked and what decision remains open. I would not rely on memory for a benefit that may matter years later. A short personal record can make a later conversation with an employer or service representative much more efficient, particularly if the question involves a transition between jobs.
There is also a handoff between the phone and a larger planning process. A mobile screen is convenient for a quick review, but I may prefer a larger display or written notes when comparing options. If I am making a decision with tax, employment, or long-term consequences, I would use the app to access the relevant information and then take the time to analyze it elsewhere. That is not a weakness unique to this app; it is a sensible boundary for mobile financial tools.
A realistic everyday scenario
Imagine that I have recently changed employers and want to understand what happened to a workplace retirement benefit. Instead of searching through old emails first, I open Benefits OnLine and sign in through the appropriate account path. I review the information shown, confirm that I am looking at the benefit connected with the former employer, and note the next available step.
If the screen answers my question, the outcome may be simple: I now know where the benefit is represented and what I need to consider next. If it raises a question, I save the wording in my notes and contact the employer or plan support channel with a precise explanation. The app has still helped because it has moved me from vague concern to a defined follow-up.
In this scenario, the real value is not dramatic automation. It is reducing the number of places I need to search before I can establish what requires attention. That is a modest benefit, but retirement administration often improves through small reductions in friction.
What the result should look like
A successful session should leave me with one of three outcomes: the information I needed, a clear next action inside the benefits process, or a well-defined question for the appropriate human support channel. If I close the app still unsure which account I reviewed or what action I took, the session was not complete, even if the login worked.
I would also separate viewing from changing. Seeing a balance or benefit description is not the same as submitting an instruction, confirming eligibility, or completing an employment-related update. Before leaving the app, I would look for a confirmation or status indication when I have taken an action. If I cannot tell whether something was submitted, I would not assume that it was.
This is where the app can be more useful than a general search engine. Search results may explain retirement concepts, but they cannot replace access to the account-specific information connected to my benefits. At the same time, the app should not be expected to answer general financial questions that belong to an adviser, tax professional, employer, or plan document.
Where the flow breaks down
The first possible break is eligibility. Benefits OnLine is not a universal retirement app, so its usefulness depends on having a relevant Merrill Lynch benefits relationship. Someone looking for a broad tracker for accounts held with unrelated providers may find the experience too narrow. In that case, an aggregation-focused finance app or the provider’s own platform may be a better fit, depending on the person’s needs.
The second break is account recovery or sign-in friction. Financial apps must be cautious about access, and that caution can make a forgotten credential or uncertain account path feel more disruptive than it would in a social app. I would avoid creating several overlapping attempts in a hurry. Instead, I would use the official recovery process and keep personal details private while resolving the issue.
A third break is interpretation. The app can put benefit information in front of me, but a concise mobile presentation may not explain every employment or retirement implication in the way I need. If I am unsure about tax treatment, rollover choices, eligibility, or the consequences of a change, I would treat the displayed information as a starting point and seek qualified guidance. The app is not a substitute for professional advice simply because it is convenient.
Device compatibility can also interrupt the process. The minimum operating-system requirement is 11, so anyone using an older device should check compatibility before planning around the app. Updating a phone may not be desirable or possible for every user. This is a practical issue rather than a feature complaint, but it affects whether the app can serve as a dependable access point.
How it compares with familiar alternatives
Compared with a general budgeting app, Benefits OnLine offers a narrower and potentially more relevant route to workplace retirement and benefit information. A budgeting app is usually better for categories, spending patterns, bills, and household cash flow. It may be easier to understand as a daily money dashboard, but it may not provide the account-specific benefits context I am trying to reach here.
Compared with using a mobile browser, a dedicated app can feel more direct because I am entering a service designed around the same benefits relationship each time. The browser may be preferable if I rarely access the account, if I need to work on a larger screen, or if I do not want another finance app installed. The app becomes more compelling when repeated phone access is part of my routine.
Compared with contacting an employer or plan representative immediately, the app can help me gather basic information before making that call. That can save time and make my question more precise. However, a representative remains the better option when records need correction, an employment transition is unclear, or the issue involves an interpretation that the screen does not settle.
Who will get the most from it
I see the strongest fit for employees, former employees, and benefit participants who already have a relevant Merrill Lynch connection and want phone access to retirement or workplace-benefit information. It is especially practical for someone who checks these details occasionally but does not want to begin every session by searching through a browser, old messages, or employer paperwork.
It may also suit a person who is organizing a job transition. The app can serve as one checkpoint in a larger checklist: identify the benefit, review the information, note the next decision, and contact the correct party if anything needs clarification. That workflow is more valuable than simply installing the app and hoping it will organize retirement planning automatically.
I would suggest skipping it if the goal is daily expense tracking, net-worth aggregation across many unrelated institutions, or educational guidance for building a retirement strategy from scratch. Those needs call for different tools. Installing a focused app and then judging it for not being a broad financial suite would be unfair, but choosing it for a job outside its purpose would still lead to disappointment.
Scale, reputation, and practical expectations
The app has passed one million installs, so it is not an obscure experiment with a tiny audience. It holds an average rating of 3.5 from around 3.4 thousand ratings, with roughly 1.1 thousand written reviews. I read those figures as a sign of a functional but mixed experience rather than a universally smooth one. For a benefits app, that seems plausible: satisfaction can depend heavily on the user’s plan, account status, device, and the exact task being attempted.
The developer is Merrill Lynch, Pierce, Fenner, and Smith Inc., and the app was released on October 1, 2018. Its history gives it a place in an established benefits-access workflow, while the version number shows that it continues to be maintained. Still, a long-running app is not automatically a perfect fit for every plan or phone. I would judge it by whether it helps me complete my particular benefits task with less confusion.
My recommendation after using the workflow
I would keep Benefits OnLine installed if my employer or retirement arrangement makes it relevant and I expect to check those benefits from my phone more than once. Its best quality is focus: it gives a specific kind of financial information a clear home instead of mixing it with unrelated spending features. That focus can make a stressful administrative task feel more manageable.
I would approach it with realistic expectations. It is not the app I would open to plan a grocery budget, compare every account I own, or receive a complete retirement education. It is a focused access point, and the quality of the overall experience depends on the handoff between the app, the employer, the plan, and my own follow-through.
My final view is positive but selective. If I am already connected to the supported Merrill Lynch benefits service, the free download is a sensible way to make retirement and workplace-benefit checks more convenient. I would use it to gather account-specific information, document what I find, and identify the next step. I would not let its convenience push me into rushing a long-term decision. Used that way, Benefits OnLine earns its place as a practical companion for benefit administration, even though it is not a complete financial-planning solution.
Frequently Asked Questions
01What is Benefits OnLine?
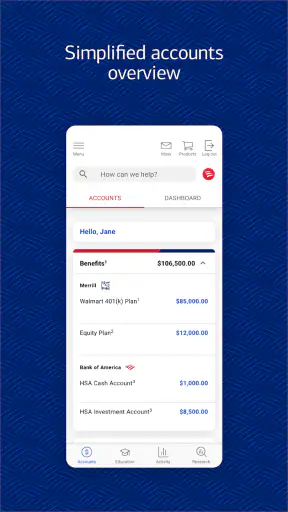
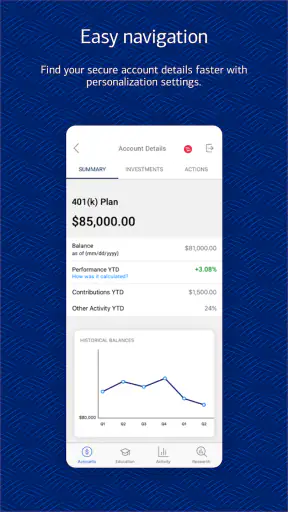
Benefits OnLine is a digital platform designed to help eligible users access and manage information about workplace benefit plans, including retirement savings and related account services. After signing in, users may be able to review balances, monitor contributions, check investment details, access statements, and find educational resources. Available features can vary depending on the employer, plan provider, account type, and region.
02Who can use the Benefits OnLine app?
The app is generally intended for participants enrolled in an eligible employer-sponsored benefits or retirement plan supported by Benefits OnLine. You may need an existing account, participant identification details, or registration information supplied by your employer or plan administrator. If your organization does not use a compatible plan, downloading the app alone may not provide access to its main features.
03What can I do through Benefits OnLine?
Depending on your plan, Benefits OnLine may allow you to view account balances, review transactions and contributions, examine investment allocations, access statements and tax documents, update certain personal details, and use calculators or planning tools. Some users may also be able to initiate eligible transactions or contact support. The exact menu and available actions depend on the rules of your specific benefits plan.
04Is Benefits OnLine secure to use?
Benefits OnLine typically requires account authentication and may use security measures such as encrypted connections, password protection, device verification, and additional identity checks. However, users should still protect their login information, avoid signing in on untrusted devices, keep the application updated, and enable available security options. Never share verification codes or passwords, even with someone claiming to represent support.
05Is Benefits OnLine free, and should I download it?
Downloading and using the Benefits OnLine application is generally free, although your employer-sponsored plan may have its own fees, investment expenses, or transaction charges. Before installing it, confirm that your benefits provider supports the platform and that you are downloading the official version from Google Play or the Apple App Store. The app is most useful for eligible participants who want convenient mobile access to plan information.


